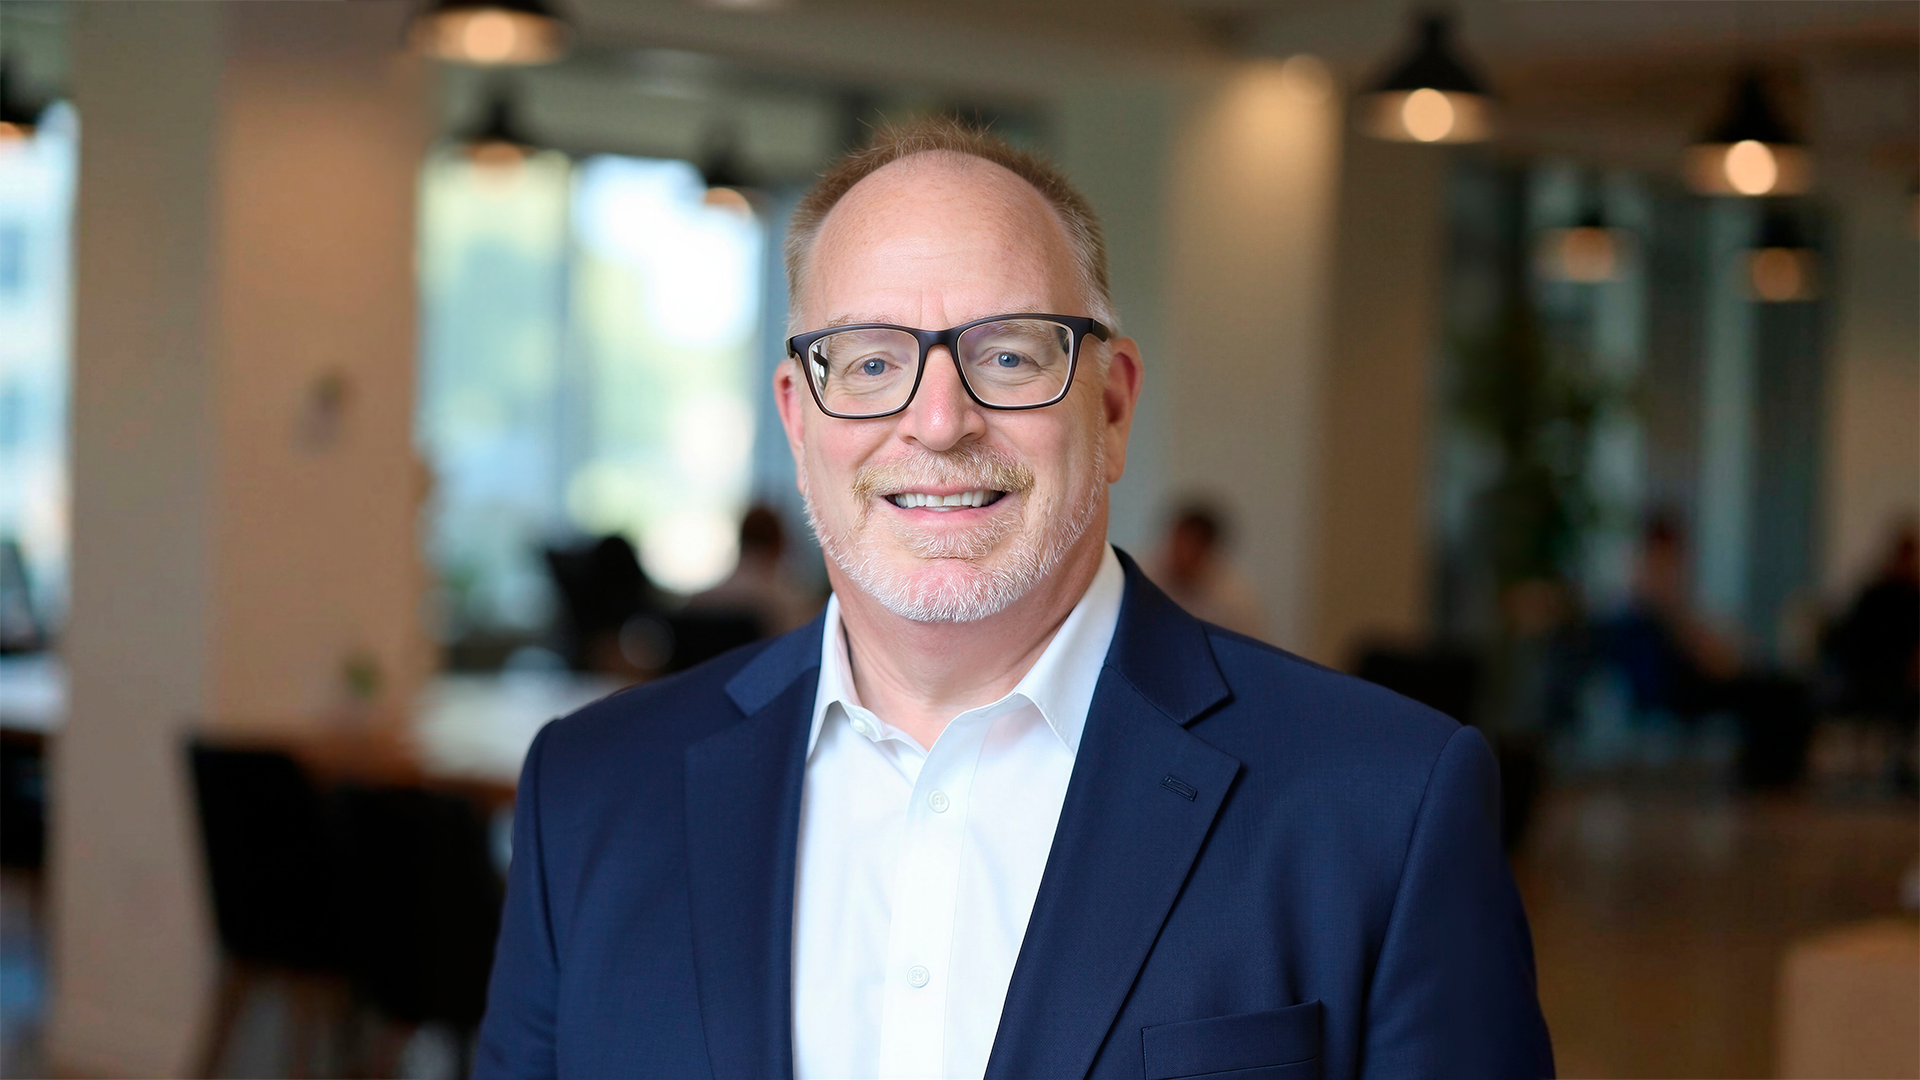

The question most owners of small and mid-sized businesses ask about a chief financial officer (CFO) is whether they can afford one. That framing is the problem. It treats senior financial leadership as a luxury purchase rather than a capability, and it quietly assumes that a bookkeeper plus a tax accountant adds up to the same thing. It does not. Douglas Prohaski, Chief Executive Officer of Prohaski Accounting & Finance, argues that the decision has little to do with payroll budget. “The decision shouldn’t simply be about whether a business can afford a full-time CFO,” he says. “It should be about what level of financial leadership the business needs and how that expertise can deliver the greatest value.” The distinction matters because the cost of going without is rarely visible on any report an owner currently reads.
The Gap Between Keeping Records And Running A Business
Most companies of consequence already have someone competent handling the books. A controller closes the month, an accountant files the returns, and the bank gets its statements. What is missing is anyone whose job it is to take that information and do something with it. Prohaski describes the gap plainly: many businesses “have capable accountants or controllers who manage their day-to-day financial activities. What they may not have is someone focused on using that financial information to improve business performance, anticipate challenges, and help ownership make better decisions.”
That absence produces a specific and recognizable failure. Revenue climbs, the owner feels good about it, and profitability quietly erodes underneath. “A company can be growing sales while becoming less profitable or consuming more cash, often without management recognizing the underlying causes,” Prohaski says. The income statement exists, but it is being read as a scorecard rather than used as a management tool. Cash gets the same treatment. Owners watch the bank balance and the reported earnings and conclude they understand their position. Prohaski singles out the statement of cash flows as the most underused document in the small-business financial package. When he walks owners through it, he says, “they quickly recognize its value in understanding where cash comes from, where it goes, and why profitability doesn’t always translate into cash.” That realization usually arrives later than it should.
Financial Problems With Operational Causes
The more consequential point in Prohaski’s argument is that the numbers are rarely where the problem lives. A margin that has slipped two points is a symptom. The cause sits in pricing, in a process that wastes labor, in how people are staffed, in which customers are absorbing capacity that could be sold more profitably elsewhere. “Financial problems often have operational causes,” he says. “Declining margins might stem from pricing, inefficient processes, staffing, or how resources are utilized. Understanding the business beyond its financial statements is essential to identifying those issues.” A CFO who only reads statements will diagnose an expense problem and recommend cutting costs, which is frequently the wrong answer applied to the wrong department.
Prohaski frames the work as connecting financial performance to the underlying economics of the business, and he is explicit that the statements alone will not get you there. “Understanding the relationships between pricing, productivity, capacity, customer profitability, and resource allocation often reveals opportunities that aren’t immediately apparent in the financial results.” The second half of the discipline is harder than the analysis and gets far less attention. Finding an opportunity is the easy part. “Sustainable improvement requires recommendations that are operationally practical, supported by management, and measurable over time.” Plenty of advisory work dies at the deck stage because nobody asked whether the operating team could execute it, or wanted to.
What AI Changes And What It Does Not
The economics of this work have shifted, and the shift favors smaller companies. Automation has compressed the time between a transaction occurring and management knowing about it. Prohaski has helped businesses cut their month-end close to one or two days against traditional processes that can run weeks, which changes the character of the information entirely. A close that lands three weeks after period end is a history lesson. One that lands in 48 hours is a decision tool. The value is not simply that the numbers arrive sooner, but that management can identify problems earlier, understand their causes while there is still time to respond, and develop and implement solutions before small issues become expensive ones. “Having reliable financial information available almost immediately gives management a significant advantage in identifying issues and responding to changing conditions,” he says.
The second effect is on reporting infrastructure. Custom dashboards and scorecards that blend financial and operational data used to require an IT budget and a development cycle, which put them out of reach for companies below a certain size. That barrier has largely fallen. “Smaller companies can access the same type of management information that previously required large IT budgets and extensive development resources,” Prohaski says. The strategic consequence is that information advantage is no longer something larger competitors can simply buy. What remains scarce is judgment. “Technology alone doesn’t create better business outcomes. The real value comes from knowing which metrics matter, understanding what drives performance, and translating that information into strategic decisions.” Faster bad analysis is still bad analysis, delivered sooner. But when reliable information is paired with sound judgment, speed becomes a competitive advantage: leaders can act on emerging problems sooner, test whether their solutions are working, and adjust course before the costs compound.
That is also why the fractional structure fits the moment. Involvement can scale from a few hours a week to something far more intensive during growth, transition, or distress, then taper once the disciplines are embedded. Prohaski’s read on the next few years is that the winners will be the companies that spot trouble early enough to act cheaply. They will be the ones with reliable forecasting, effective cash management, meaningful performance measures, and clear accountability. “I don’t believe business owners are looking for more reports or complicated financial models,” he says. “They’re looking for solutions to real business challenges.” The reporting is not the product. The decisions are.
Follow Douglas Prohaski on LinkedIn for more insights on fractional financial leadership, profitability improvement, and cash flow management.